
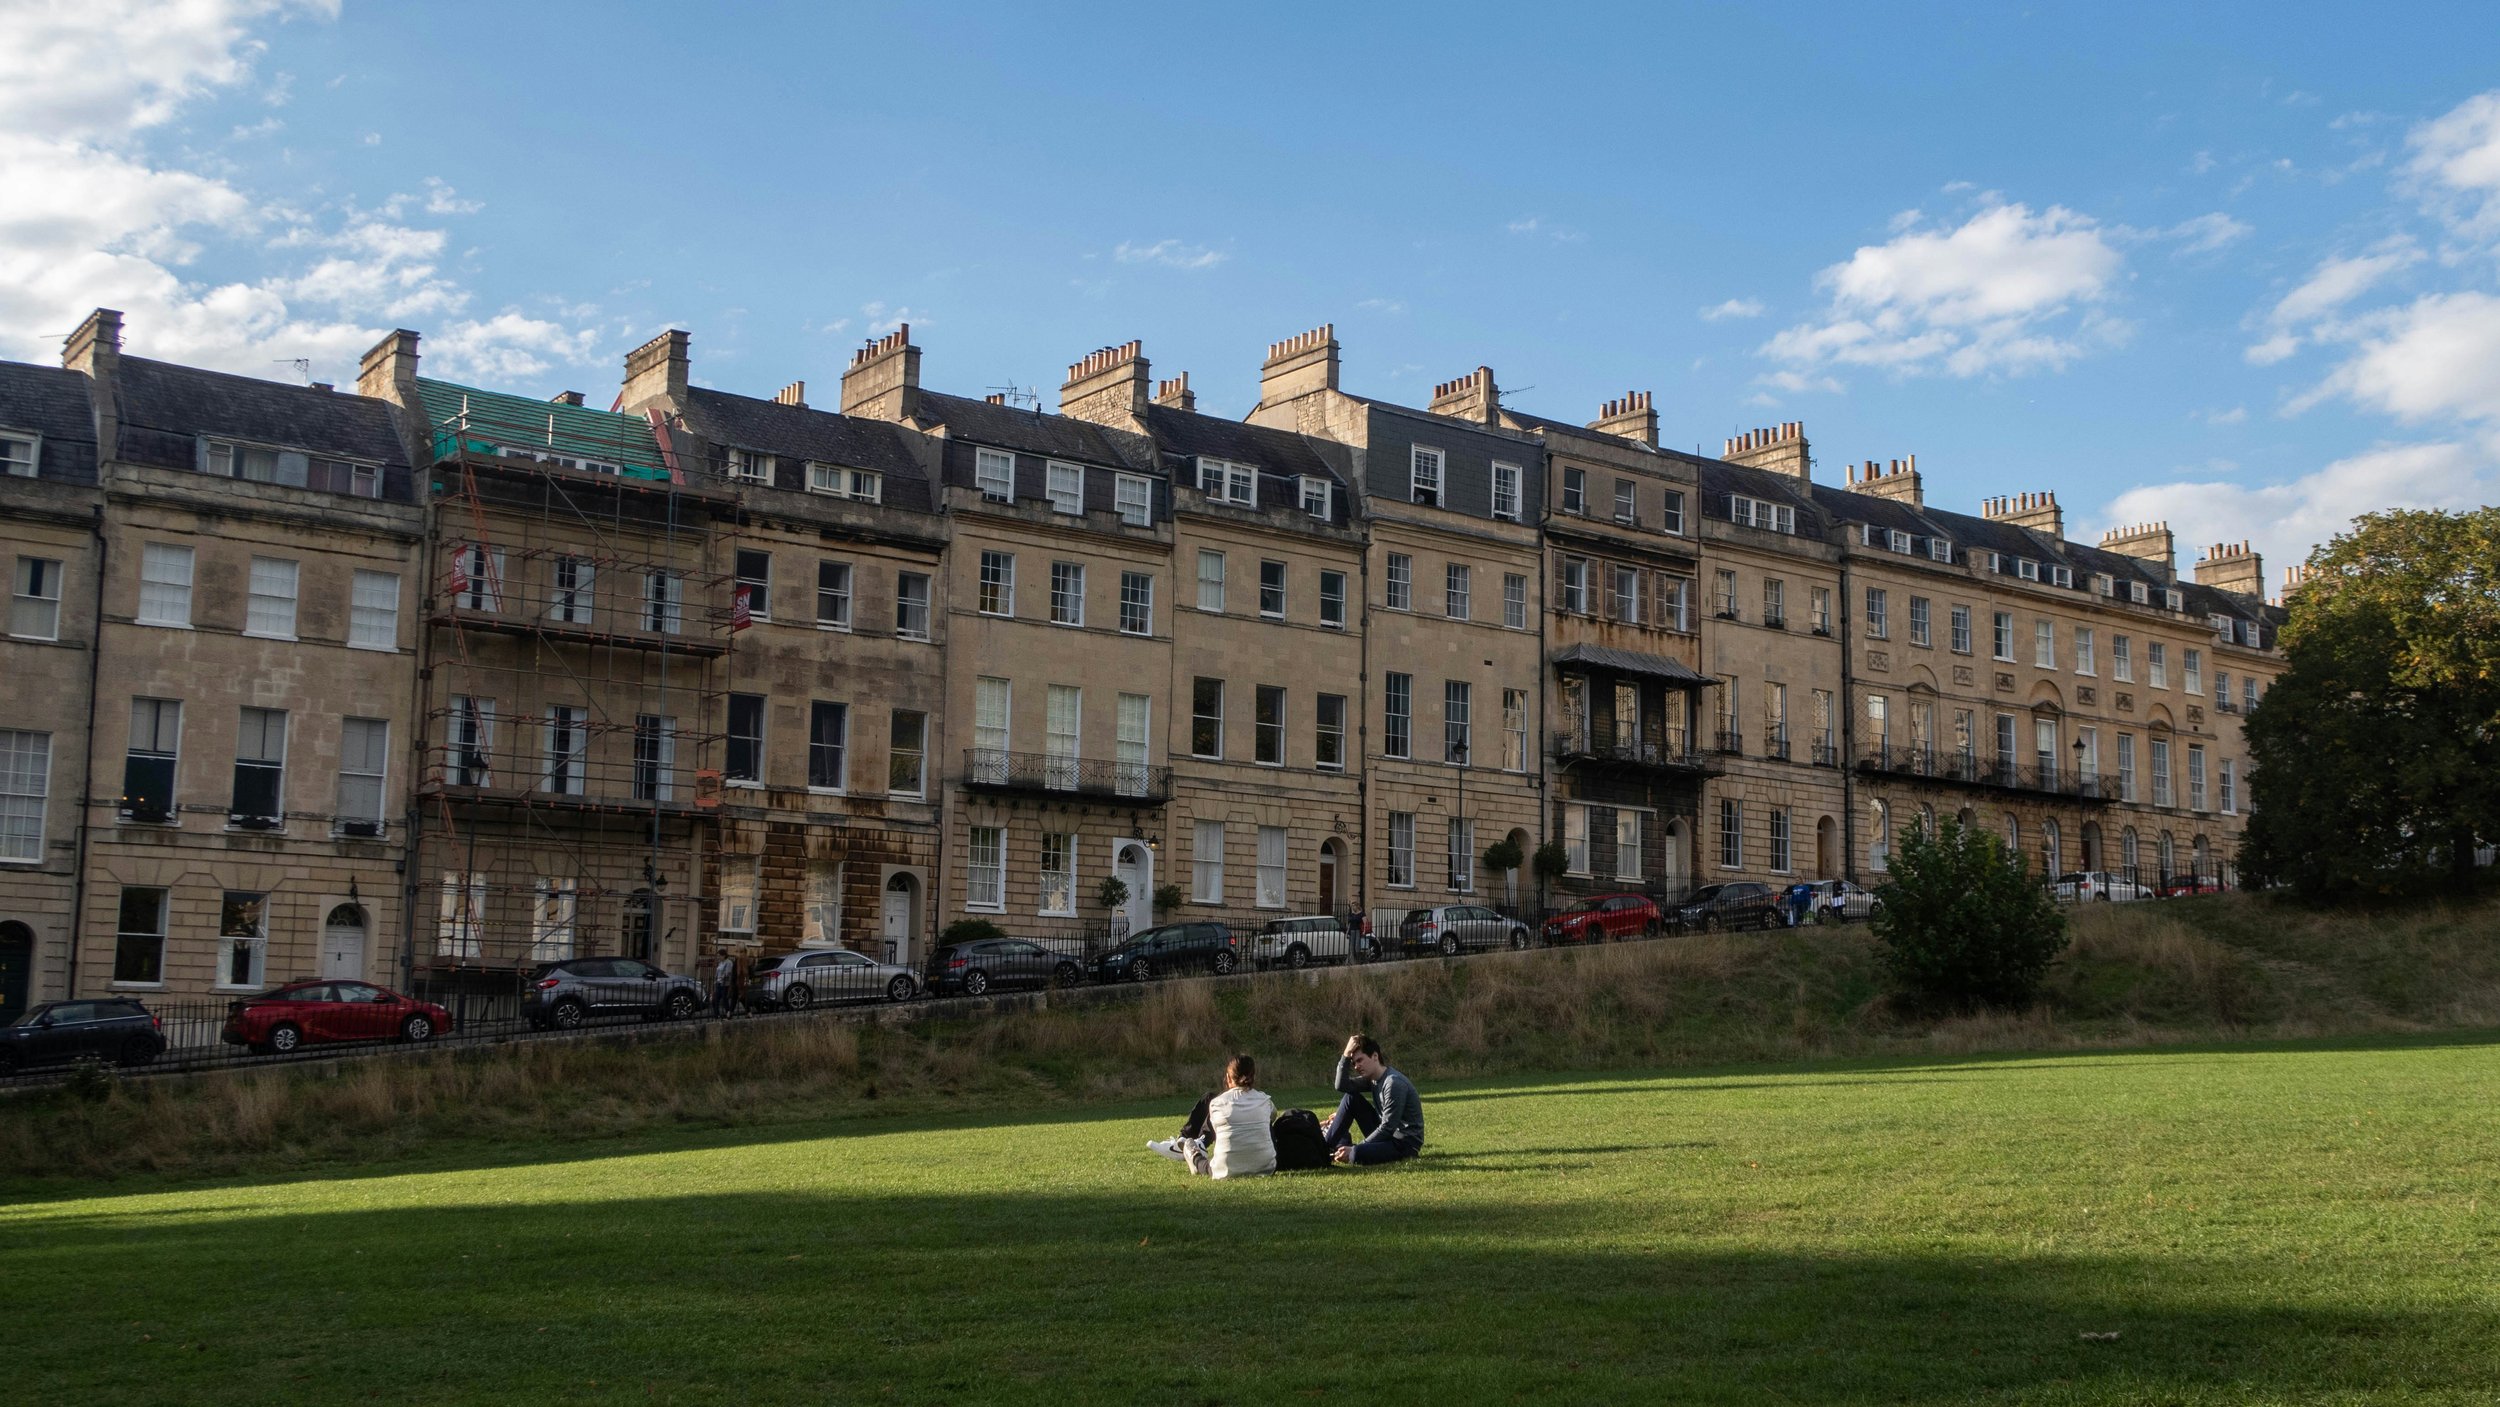
Buying your first home in Bath is exciting, but working out what you can afford, how much deposit you'll need and which mortgage to choose can feel like a lot to take in. Understanding your mortgage budget before you start seriously looking at properties can make the whole process considerably simpler.
And in Bath, where property types and prices can vary enormously from one street to another, knowing where you stand financially is particularly useful.
Start with your budget, not Rightmove
It's very easy to start with the houses.
We'd start with the numbers.
Before you fall in love with a particular property, it's useful to understand roughly how much you may be able to borrow, the deposit you'll need and what the monthly repayments might look like.
A mortgage adviser can help you establish your potential budget and, when you're ready, arrange an Agreement in Principle.
Then you can search for a home with a much clearer idea of what's realistic.
How much deposit will I need?
Many first-time buyers will be looking at mortgages requiring a deposit of around 5% or more of the purchase price, although availability and lending criteria vary.
Increasing your deposit can potentially give you access to a wider choice of mortgages or different interest rates.
But don't forget that you'll need money for more than the deposit.
Legal fees, surveys, mortgage fees, moving costs and any applicable Stamp Duty should all be considered.
And keeping some savings back for the inevitable things you'll discover you need after moving in isn't a bad idea either.
Buying in Bath
One of the wonderful things about Bath is the variety of property available.
It's also something mortgage lenders sometimes need to consider.
Alongside more conventional modern houses, the city has Georgian and Victorian properties, listed buildings, converted apartments and leasehold flats.
Some properties may require a little more investigation from the lender, valuer or solicitor than others.
That doesn't mean they're unmortgageable. It simply makes it important to understand exactly what you're buying.
What about leasehold flats?
If you're considering a flat, it's important to understand the lease as well as the property itself.
Your solicitor will investigate matters such as the remaining lease term, service charges and other obligations.
Mortgage lenders also have criteria relating to leasehold properties, so it's worth raising any potential concerns early.
Do I need a survey?
Your mortgage lender will normally carry out the valuation it requires for mortgage purposes, but this isn't the same thing as having a detailed survey carried out for you.
With Bath's abundance of older properties, getting appropriate advice about the condition of the home you're buying can be particularly worthwhile.
A survey could identify issues that aren't immediately obvious during a viewing.
I've found somewhere. What happens now?
Once you've had an offer accepted, you'll usually instruct a solicitor or conveyancer and progress your mortgage application.
The lender will assess your application and the property. Meanwhile, your solicitor will carry out the legal work involved in the purchase.
If everything is satisfactory, your lender can issue your formal mortgage offer.
Your solicitor will then work towards exchange of contracts and, ultimately, completion.
And eventually someone hands you the keys.
Do I need a local mortgage adviser?
Your mortgage adviser doesn't necessarily need to live in the same city as the property you're buying.
But there's something reassuring about talking to somebody who understands the area and the kinds of properties you're likely to encounter.
Marvellous is based in Bath and provides personal mortgage advice to first-time buyers here and further afield.
We'll help you understand how much you may be able to borrow, look at mortgage options that suit your circumstances and guide you through the application.
And if this is your first mortgage, there really is no such thing as a silly question.
Thinking about buying your first home in Bath?
You don't need to have found the house yet.
Come and talk to us about your income, savings and plans and we'll help you understand what your first step should be.
Your first home. That's a marvellous kind of feeling.
The information in this guide is for general information only and isn't intended as personal mortgage or financial advice. Mortgage products, rates, lending criteria and individual circumstances vary, so it's important to get advice that's right for you.
Your home may be repossessed if you do not keep up repayments on your mortgage.